All Categories
Featured
Emergency Mortgage Help to Protect Your Home
Table of Contents
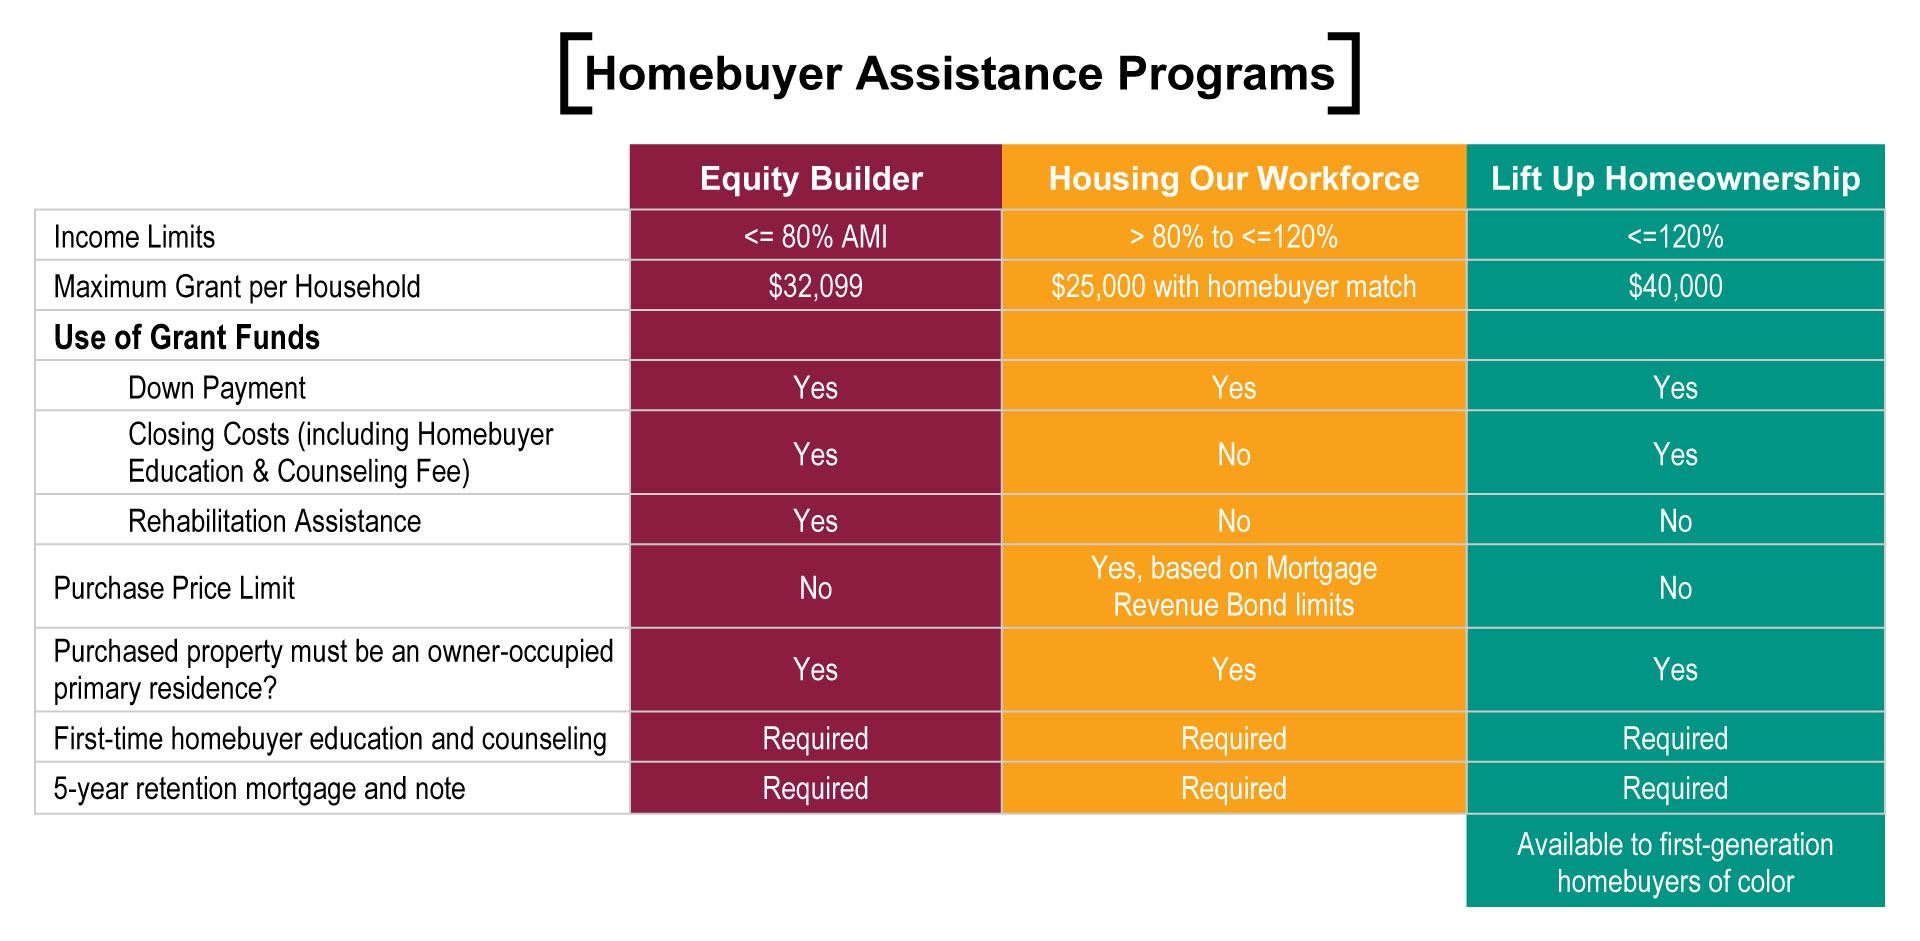
As an FHLBNY member, you have access to our novice property buyer programs to increase inexpensive homeownership in your community. Each year, to get involved in these programs and get an allocation of funds for dispensation to eligible homes, members need to initially enroll in the round. HDP funds allow you to provide grants that assist cover down payment, closing costs and property buyer therapy services for eligible homebuyers who fulfill certain income and additional requirements as specified by each of the program criteria listed below:.
The growth reacts to feedback and concerns from property owners seeking to restore and adds to the Governor's work to help supply LA firestorm survivors with monetary healing. The Governor is continuing the state's efforts to support survivors as the Trump administration turns its back on them by withholding disaster aid.
Under the broadened program, eligible property owners may get 12 months of home loan payments, paid directly to their mortgage servicers. This is a fourfold boost of the program, which formerly provided three months of relief. Help is available to homeowners who are current on their mortgage, in forbearance, or behind on payments.
New Federal Grants to Help Homeowners
In addition, the program will now conceal to $100,000 in payments, up from $20,000. This will enable families to make the most of the 12-month growth, using families major monetary relief when they require it most, enabling them to focus their own funds on fundamental needs, alternative real estate, and restoring.
Lots of households impacted by the LA fires have actually been on forbearance for a year now and have not made a home mortgage payment given that the fires started. By providing a complete year of home mortgage help and broadening earnings eligibility, we're making it clear that this assistance is real, available, and planned for households who are still recovering." Far, the state has paid $6.5 M to 793 recipients of current natural disasters the huge majority of which are survivors of the Palisades and Eaton fires.
How to Stop Foreclosure in 2026
The financing is now offered to much more survivors. Earnings limits have actually increased, so more households can get approved for help. In Los Angeles County, families with a combined yearly income of as much as $281,400 now certify. This reflects a $70,000 increase from the previous limitation. Income limitations vary by county, in locations like Butte County, earnings limitations are now $255,000.
The, administered by the California Housing Financing Agency (CalHFA), was launched to provide direct home mortgage relief to homeowners whose main houses were ruined or rendered uninhabitable by certifying disasters. Considering that its launch in June of 2025, the program has actually helped disaster-impacted property owners across California support their real estate while navigating insurance coverage claims and increasing building expenses.
How to Handle Loan Debt Smartly in 2026
"I tell people who are going through this to apply, because I did. The assistance I received relieved a huge amount of tension throughout an extremely tough time.
How to Stop Foreclosure in 2026Executive Order 14393 By the authority vested in me as President by the Constitution and the laws of the United States of America, it is thus purchased: Section 1. Purpose. Every American seeking to purchase a home ought to have access to a mortgage from a dependable loan provider, at a rate commensurate with his/her creditworthiness.
These burdens have actually added to a substantial decrease in bank participation in home mortgage lending. Neighborhood banks, normally organizations with fewer than $30 billion in possessions, have actually been specifically affected. The regulatory and guideline modifications have actually weakened neighborhood banks' services, concentrated credit and liquidity threat outside the banking system, and resulted in decreased access to credit for some creditworthy borrowers, including rural households and low- and moderate-income households.
Reviewing Refinancing vs Short Sale Prevention
It is the policy of the United States to improve the schedule and price of home mortgage credit; tailor rules for community banks and "smaller banks" (banks with possessions fewer than $100 billion); decrease the regulative concern on neighborhood banks and otherwise assist in community bank engagement in home mortgage activity; foster innovation, growth, and consumer option in the mortgage market; modernize origination and closing standards to lower loaning expenses; get rid of regulatory distortions to the structure of the home loan market and to ensure capital and liquidity structures subject similar credit and liquidity threats to comparable regulation throughout the system; promote competition amongst mortgage loan providers of all charter types to drive down home mortgage rates; and enhance housing-finance liquidity.

Latest Posts

Comparing Mortgage Refinance Help in 2026

Key Benefits of 2026 Home Support Programs
Benefits of Early Mortgage Relief in 2026